SoFi: Bank, Invest & Loans

Screenshots
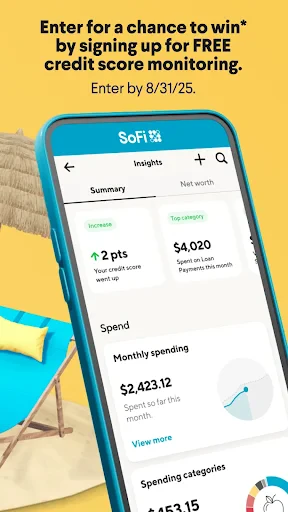
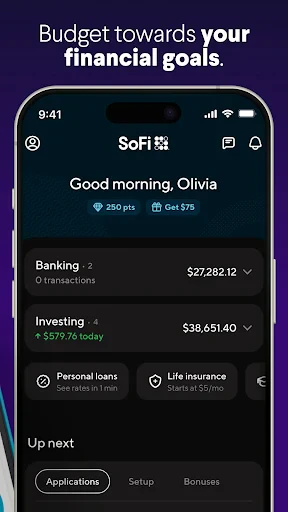
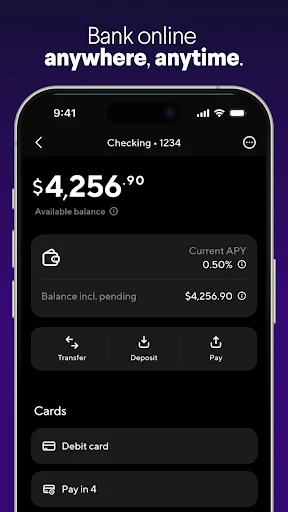
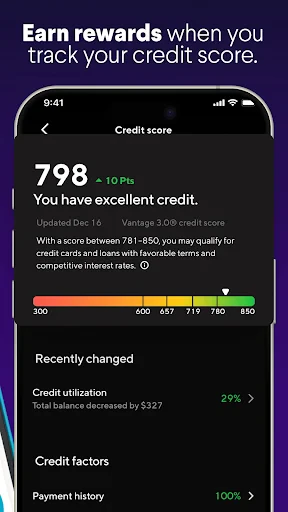
Details
- Rating
- 19.27K reviews
- Version
- 3.72.2
- Developer
- Social Finance, LLC
Analysis by Norviv
I treat a finance app differently from a game or a social feed: it needs to make everyday money tasks easy to find, but it also has to feel dependable when I’m checking a balance or weighing an important decision. SoFi: Bank, Invest & Loans brings banking, investing, saving, budgeting, and loan-related options into one place. That breadth is its main appeal, though it also means the app will suit some money routines much better than others.
What I expect from its speed
For a financial app, I care less about flashy transitions than about getting to the task I opened it for without needless friction. SoFi’s layout is designed around several kinds of money activity, so someone who only wants to check a balance may find the range of destinations broader than necessary. In my experience, the practical test is whether I can build a simple routine: open the app, review what matters, and leave without being pulled into unrelated decisions.
That distinction matters because speed is not only how quickly a screen appears. It is also how quickly I can tell which account or activity I am looking at. When banking and investing sit alongside one another, clear navigation can save more time than an animation or a shortcut. I would use the app with a specific purpose in mind—checking a deposit, reviewing a spending plan, or looking at an investment—rather than treating every visit as a general financial browsing session.
When several money tasks compete for attention
SoFi is most compelling when I want to connect decisions that would otherwise happen in separate places. For example, I might check my regular cash position before deciding how much I can comfortably set aside, then look at investment choices without switching apps. That makes it easier to keep a broad view. It does not remove the need to think carefully: a balance, a budget, and an investment are different things, and I would not treat money invested as if it were instantly available spending cash.
A realistic weekday use would be checking whether a paycheck has arrived, reviewing planned expenses, and then deciding whether there is room to save or invest. The useful habit is to set the order: confirm cash available first, account for near-term bills second, and only then consider longer-term choices. An all-in-one screen can make those steps convenient, but it cannot make an investment risk-free or a loan automatically suitable.
Reliability is also about knowing what you are doing
I judge reliability in a finance app by more than whether it opens. Labels, account context, and a clear distinction between routine banking and higher-stakes actions all matter. SoFi’s wide scope is convenient, but it asks me to stay attentive when moving between saving, trading, and borrowing. Before confirming any consequential action, I would pause to check the selected account, the amount, and the terms shown in the app. That small habit is worthwhile in any financial service, especially one that puts multiple tools within easy reach.
There is also a useful difference between an app being convenient and a service being the right home for every financial need. If I already have a bank I trust and a separate brokerage whose tools I understand, moving everything simply to reduce app switching may not be worth the disruption. I would compare the actual account features and costs that matter to me before changing established arrangements, rather than assuming that consolidation is automatically an upgrade.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Device fit and everyday use
SoFi is a free finance app from Social Finance, LLC. It has an Everyone content rating, and the Android version requires 8.0 or later. The current version is 3.72.2. It has been available since April 10, 2017, and its scale is reflected in more than 5 million installs, around 49,000 ratings, and a 4.0 average. Those figures offer useful context about its reach, but they cannot tell me how it will feel on a particular phone or whether every feature matches my needs.
I would keep the app updated and make sure my device has enough room for the ordinary demands of the apps I rely on, but I would not assume that a finance app needs powerful hardware based on its range of services alone. If an older phone feels sluggish, I would first separate general device performance from the app’s own behavior: close unnecessary background activity, restart the device if it has been running for a long time, and try again. For an important transaction, I would avoid relying on a rushed session or an unstable connection; taking a moment to confirm the result is a sensible routine regardless of the app.
On iOS, the same decision should start with checking that the app supports the device and operating system in use. I would also consider whether I am comfortable managing sensitive financial activity on that phone, keeping it protected with the security tools available on the device, and using a private connection when handling account details. These are sensible habits for any mobile finance service, not special performance claims about SoFi.
All-In-One Financial Hub
One of the first things that struck me about SoFi: Bank, Invest & Loans is how it bundles all your financial needs into a single app. Seriously, it’s like having a Swiss Army knife for your finances. You can manage your checking and savings accounts, explore investment options, and even apply for loans, all without jumping between different apps or websites. It’s genuinely a one-stop shop.
Banking Features
Starting with the basics, SoFi offers a pretty robust banking experience. You get a checking account without any hidden fees, and there’s also a nice savings account with competitive interest rates. They even throw in some cool perks like early direct deposit, making sure you can access your paycheck up to two days early. Honestly, who doesn’t love getting paid a little early?
Investing Made Easy
Now, onto the investment side of things. If you’re new to investing, SoFi’s got you covered with automated investing options. You can set your goals, and the app helps you build a diversified portfolio. For the more adventurous folks, there are active investing options where you can pick and choose your stocks and ETFs. It's pretty user-friendly, so no need to feel overwhelmed.
Loans and Refinancing
Need a loan or looking to refinance? SoFi offers personal loans with no origination fees and competitive rates. The application process is straightforward, and you can check your rates without affecting your credit score. It’s a handy feature if you’re shopping around for the best deal. Plus, if you’re burdened with student loans, SoFi offers refinancing options that might help ease that load.
User Experience
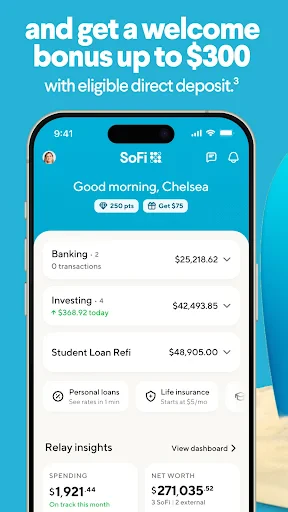
The app itself is sleek and intuitive. Navigation is smooth, and everything is where you’d expect it to be. I didn’t find myself lost or confused at any point, which is always a win in my book. Plus, their customer support is just a chat away if you ever run into any hiccups.
Who will get the most from combining services
The app makes the most sense to me if I want a central place to keep tabs on cash and explore other financial tasks without maintaining several separate apps. Someone who is just beginning to invest may appreciate having automated and self-directed approaches side by side: the first can suit a hands-off routine, while the second gives more control over individual stock and ETF choices. I would still take time to understand what I am selecting rather than treating a friendly interface as a substitute for learning the risks.
It may be less attractive if I want a specialist tool above all else. A dedicated brokerage can be a better fit for someone who relies on advanced research or a particular trading workflow, while a person satisfied with an existing bank may see little reason to move everyday deposits. Similarly, loan shopping should involve comparing offers and repayment terms, not choosing the first convenient application. SoFi’s range is a reason to consider it, not proof that it is the best option for every product.
A few habits that make the combination more useful
One practical approach is to decide what each part of the app is for before using it regularly. I would keep short-term spending money mentally separate from savings and investments, then review those areas on different schedules. That helps prevent a reassuring overall balance from obscuring the fact that some money may be intended for bills or may be exposed to investment changes. It is a small organizational habit, but it makes an all-in-one service easier to use thoughtfully.
For goal-based investing, I would begin with a goal I can describe in plain language and a time horizon that makes sense to me, then revisit it when my circumstances change rather than reacting to every market movement. For active investing, I would decide in advance how much time and attention I am willing to give it. Having both options in one app is convenient, but it can also make frequent checking tempting; convenience should not be confused with a reason to trade more often.
When considering a loan or refinancing, I would use the rate-checking step as a way to compare, not as a commitment to proceed. Before accepting any offer, I would read the repayment schedule and total obligations carefully and check whether the payment fits my budget. The same principle applies to savings: an attractive rate is only one consideration, and I would look at the account terms that matter to my own plans before moving money.
Where it sits among banking alternatives
Compared with using a traditional bank app for deposits and a separate brokerage for investments, SoFi’s strongest advantage is having those activities under one roof. That can reduce app switching and make it easier to see how cash decisions relate to longer-term plans. The trade-off is that a combined app may not provide the depth or familiar specialist workflow that a person already gets from a dedicated institution. I would compare the specific services I use, not just count how many icons I can remove from my phone.
Compared with a budgeting-only app, SoFi’s appeal is that budgeting sits alongside account, investing, and borrowing options rather than being the whole experience. If my main challenge is detailed household planning, category-by-category tracking, or coordinating a complex shared budget, a dedicated budgeting tool may be more appropriate. If I mainly want to check my finances and take several common money actions from one place, the broader setup may be more useful.
People also ask whether the app is free to download. Yes, SoFi is listed as free, though I would still review the terms associated with any financial product I choose. And is it only for experienced investors? No: automated investing is intended to make getting started more approachable, while active investing offers another route for people who want to select stocks and ETFs themselves. Either way, I would not invest money I may need for near-term expenses.
What to expect if something feels slow
Because I cannot infer a particular phone’s performance from an app’s feature list, I would keep expectations practical: screen changes, account information, and other online activity can be affected by the device and connection as well as by the service. If a page takes longer than expected, I would avoid tapping repeatedly or submitting the same action again. I would wait, check whether the app shows a completed or pending result, and confirm the relevant account activity before trying again. That reduces the chance of confusing a delayed screen with a failed transaction.
If access is interrupted, I would use the app’s support option for a problem I cannot resolve and keep a record of what I was trying to do, without sharing sensitive credentials in an informal message. A financial app should be approached more patiently than a casual utility: if I am unsure whether a consequential action went through, I would verify its status before repeating it. That is a sensible recovery habit, not a claim that interruptions are common.
Overall, SoFi: Bank, Invest & Loans is a solid choice for anyone looking to simplify their financial management. Whether you’re just dipping your toes into the world of investing or need a reliable banking solution, SoFi has something to offer. It’s like having a personal financial advisor in your pocket, without the hefty fees.
My performance verdict
I see SoFi’s performance proposition as convenience more than raw speed: its value is having banking and several other financial activities available in a shared environment. I would choose it if that combination fits the way I manage money, and I would keep a clear routine so the range of choices stays helpful rather than distracting. The app’s reach and established presence are reassuring context, but my decision would still come down to whether its accounts, investment approach, and loan options suit my real needs.
If I want one place to handle everyday banking and explore saving or investing, it is worth considering. If I need a specialist brokerage, a highly focused budgeting workflow, or already have financial arrangements that work well, a separate service may be the better choice. My advice is to start with the task you actually want to improve, compare the relevant terms, and only consolidate more of your financial life if the convenience proves useful in practice.
Frequently Asked Questions
01What features does the SoFi app offer?
The SoFi app provides a comprehensive suite of financial services, including banking, investing, and loan management. Users can open a checking or savings account, invest in stocks and ETFs, or apply for personal and student loans. The app also offers budgeting tools and financial advice to help users manage their finances effectively.
02Is the SoFi app secure to use?
Yes, the SoFi app takes security seriously by implementing advanced encryption and security protocols. It requires multi-factor authentication and regularly monitors accounts for suspicious activity. Additionally, SoFi is insured by the FDIC, providing extra peace of mind for users concerned about the safety of their funds.
03Are there any fees associated with using SoFi?
SoFi prides itself on offering a fee-free banking experience. There are no account maintenance fees, overdraft fees, or minimum balance requirements. However, fees may apply for certain services, such as wire transfers. It's important to review the fee schedule in the app or on the SoFi website for detailed information.
04Can I access customer support through the SoFi app?
Yes, the SoFi app provides access to customer support. Users can contact support via in-app chat, phone, or email. The app also features a comprehensive help center with FAQs and guides to assist with common queries. Support is known for being responsive and helpful, making it easy to resolve issues.
05How does SoFi's investing feature work?
SoFi's investing feature allows users to trade stocks, ETFs, and cryptocurrency with no commissions. The app offers both active and automated investing options, catering to different user preferences. Users can also access educational resources and market insights to make informed investment decisions, helping both beginners and experienced investors.


